Roof Replacement Cost in Houston (2026 Guide)
You want a straight answer about money, and most roofing websites won't give you one. Here's ours: we can't tell you what your roof costs from a web page — nobody honestly can — but we can show you the real ranges Houston homeowners are paying in 2026, exactly what moves the number up or down, and how to spot a quote that's hiding something. Written by a roofer who's priced Houston roofs since 1985.
On this page
The Short, Honest Answer
In 2026, most single-family roof replacements in the greater Houston area with architectural shingle land somewhere in the low-to-mid five figures. Smaller, simpler, single-story roofs come in under that; large, steep, or complicated roofs go over it. Standing-seam metal typically runs roughly two to three times the cost of the same roof in shingle.
That's a wide bracket, and it's wide on purpose. Any website that quotes you a tighter number without seeing your roof is guessing — and a guess dressed up as a price is the first sales tactic this guide will teach you to distrust. The spread between the cheapest and most expensive version of your roof is driven by six specific factors, and every one of them is measurable during a free inspection. That's why our promise isn't a number on a page — it's a real written quote.
The Six Factors That Actually Drive the Price
When two neighbors get quotes thousands of dollars apart, these six factors — not magic, not markup — are almost always why.
1. Roof size, measured in squares
Roofers price by the "square" — 100 square feet of roof surface. Your roof's area is bigger than your floor plan: it includes overhangs, porches, and the extra surface created by slope. A 2,000 sq ft house might carry 24–30 squares of roof. Materials and labor both scale with squares, which makes size the single biggest cost driver.
2. Pitch and complexity
A steep roof takes more safety equipment, slower work, and more crew hours than a walkable one. Valleys, dormers, skylights, chimneys, and multiple roof planes each add cut work and flashing detail — which is exactly where leaks start when it's rushed. Two houses with identical square footage can be very different jobs.
3. Tear-off and layers
A proper replacement strips everything down to the wood decking. If a previous owner layered new shingles over old ones, there's now twice the material to tear off and haul away — more labor, more disposal weight, more cost. It's also why adding a layer only moves the bill to the next owner, plus interest, so we steer customers away from it.
4. Decking condition — the honest unknown
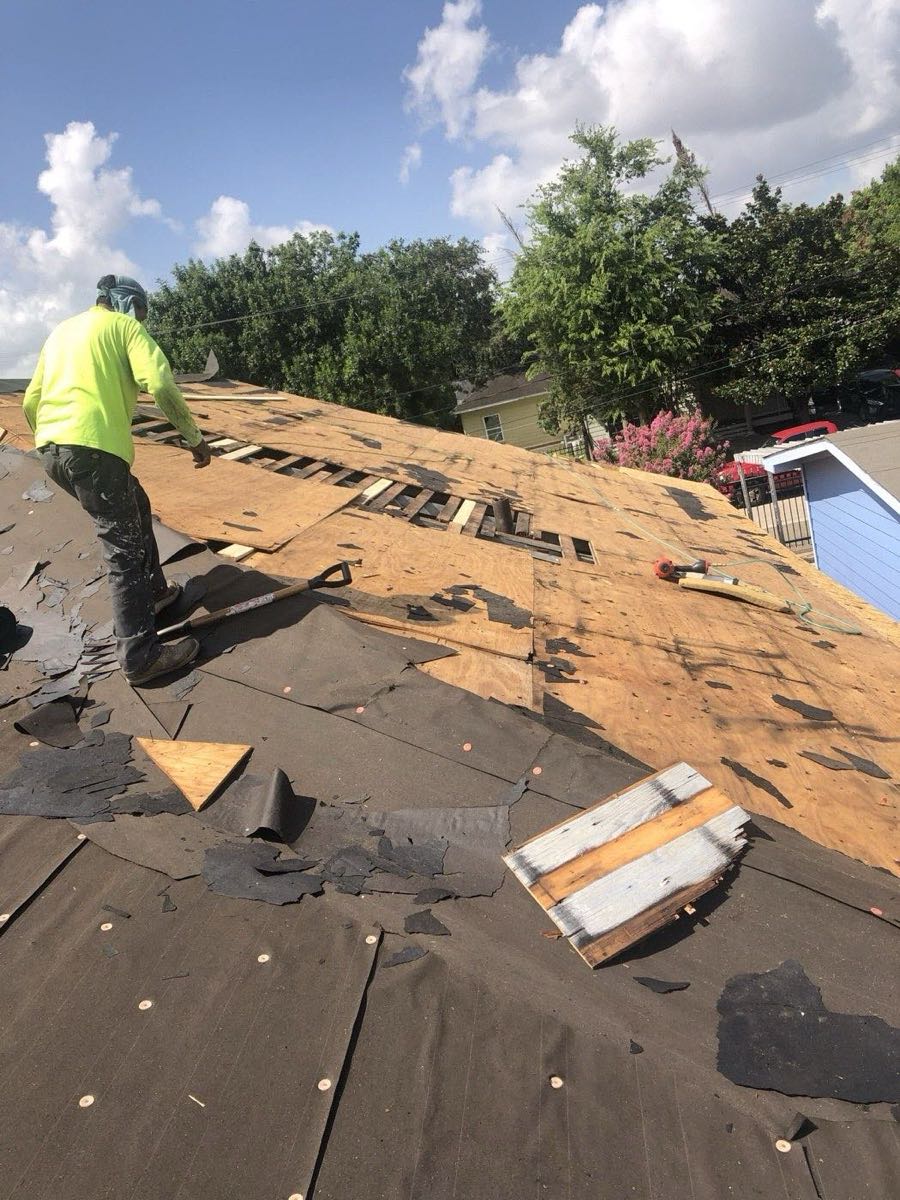
Under the shingles and underlayment is the plywood or plank decking your entire roof is nailed to. Years of Gulf humidity and slow leaks can rot it invisibly. No one can price it precisely before tear-off; what matters is how a contractor handles it — a per-sheet price in writing up front, photos of anything found, and your approval before replacement.
5. Material tier
Builder-grade 3-tab, mid-range architectural shingle, designer shingle lines, and standing-seam metal sit at meaningfully different price points — with meaningfully different lifespans and wind ratings. Architectural shingle is the sweet spot for most Houston homes; metal costs more up front and can outlast two shingle roofs.
6. Ventilation, flashing & detail work
In Houston heat, a poorly vented attic cooks shingles from underneath and can void manufacturer warranties. Correct ridge and intake ventilation, new flashing at chimneys and valleys, and new drip edge are part of a real replacement's price — and their absence is how a lowball bid gets low.
Realistic 2026 Ranges for the Houston Market
These are honest ballparks — wide by design — for what homeowners across our service area are actually paying. Only an on-site inspection can narrow them to your roof.
Architectural shingle — typical single-family home
Commonly low-to-mid five figures
The workhorse replacement for most Houston subdivisions: full tear-off, new underlayment, new flashing and drip edge, corrected ventilation, architectural shingle with a solid wind rating, disposal, and a written workmanship warranty. Smaller one-story roofs sit at the bottom of the bracket; large two-story homes with steep or cut-up rooflines push toward the top and beyond.
Standing-seam metal
Roughly 2–3× the same roof in shingle
Higher material cost and slower, more skilled installation — in exchange for the longest service life we install, excellent performance in coastal wind, and reflected summer heat. Often the right long-term math for homeowners planning to stay put, especially closer to the coast.
Partial repair instead of replacement
A fraction of replacement cost — when it's the right call
Not every aging roof needs replacing. Isolated storm damage, a single failing flashing detail, or a small leak on an otherwise sound roof is often a repair, and we'll tell you when it is — even though it's the smaller ticket. A repair quote from us is a sign the inspection was honest, not that we missed something. Repair brackets are in the roof repair cost guide.
Why won't we print tighter numbers? Because we'd be making them up. Materials pricing moves, and the six factors above swing the total by more than any online estimate's margin of error. A range you can't act on is trivia; a written quote follows after you ask for one — here's exactly what the free estimate includes.
Size Your Roof — the Honest Estimator
Online roof calculators print a dollar figure by making numbers up. Here's what CAN be computed honestly from your answers: your roof's approximate size, and where it lands in the Houston brackets above. The real number still takes an inspection — and comes in writing.
That's as far as honest math goes without a ladder. For a written number:
Get My Free Quote →
Runs entirely in your browser — nothing you type here is sent or stored. Roof area is geometry (footprint × pitch); brackets are the published ranges above, not invented dollars.
Why the Cheapest Bid Is Usually the Most Expensive Roof
When a bid comes in dramatically under the others, the money didn't disappear — it came out of the roof. After four decades of being called in to fix "bargain" roofs, we can tell you exactly where it usually comes from:
- Old flashing reused. Flashing at chimneys, walls, and valleys is where most leaks start. Reusing corroded flashing under new shingles saves a few hundred dollars and buys a leak with a new-roof price tag on top of it.
- Ventilation skipped. Nothing looks different from the street, but the attic runs hotter, the shingles age years faster, and the manufacturer warranty may be void from day one.
- Layering instead of tear-off. Nailing over the old roof skips labor and disposal — and skips the only chance to see the decking. Whatever is rotting under there keeps rotting under your "new" roof.
- Bottom-tier materials at top-tier names. "30-year shingle" on the quote, the thinnest line of it on the truck. If the quote doesn't name the manufacturer and product line, you can't compare it to anything.
- No real insurance or warranty behind it. A crew without liability coverage and workers' comp is cheaper to run. You find out whose problem that is when someone's hurt on your property or the roof leaks in year two and the phone number is dead.
A roof is one of the few purchases where the failure shows up years after the payment. The cheapest bid wins on the day you sign and loses every rainy day after. What you're actually buying — from anyone — is the confidence that the company will still exist, and still answer the phone, when it matters. That's the real reason to weight a 40-year local track record over a door-knocker's price.
How Insurance Changes the Math Entirely
Everything above assumes you're paying out of pocket. After hail or hurricane-force wind — regular events in Harris and Galveston counties — a replacement often isn't an out-of-pocket project at all. It's an insurance claim, and the math changes completely: on an approved storm-damage claim, your cost is your deductible (commonly 1–2% of your home's insured value on Texas windstorm/hail policies), and the insurer funds the rest of the covered replacement.
The difference between a paid claim and a denied one usually comes down to documentation and deadlines — storm damage like hail bruising and wind-lifted shingles frequently isn't visible from the ground, and Texas policies limit how long you have to file. We've walked Houston homeowners through this process for decades: inspect, document, meet the adjuster on your roof, and do the work to your policy's requirements.
One line you'll hear from storm chasers that you should treat as a walk-away: "We'll take care of your deductible." Waiving or absorbing a deductible is illegal in Texas (more on that in the FAQ below) — and a contractor willing to commit fraud on the paperwork is telling you how they'll treat the parts of the roof you can't see.
How storm damage & insurance claims work → • Our insurance help →
How Payment Usually Works
Payment structure is one of the clearest honesty tells in this industry, so here's what reasonable looks like in general terms:
- Written quote first, with any change shown to you before it happens. The only legitimate mid-job change is decking found at tear-off — at the per-sheet rate already on your quote, photographed, and approved by you before it happens.
- No large cash payment before materials are on site. A modest deposit or material draw at delivery is normal on retail jobs; "pay half up front to hold your spot" from a company you found yesterday is how homeowners fund someone else's disappearance.
- Insurance jobs follow the claim's disbursement schedule. Insurers typically release funds in stages (initial payment, then recoverable depreciation after completion), and payment timing tracks that — your out-of-pocket remains the deductible.
- Financing is a conversation, not a trap. If spreading the cost matters, ask during the quote — we'll walk through current options before you commit. Be wary of anyone who leads with the monthly payment to keep you from looking at the total.
- Final payment after the final walkthrough — cleanup done, magnet sweep run, warranty documents in your hand.
Red Flags in a Roofing Quote
Compare scope, not just bottom lines. Any of these on a quote — or in the pitch that came with it — is a reason to slow down:
- A one-line quote. "New roof — $X" with no materials named, no scope, no squares. You can't compare it, and that's the point of writing it that way.
- An expiring price. "This number is only good if you sign today." Real prices survive a week of thinking. Manufactured urgency exists to beat the other quotes you haven't gotten yet.
- "We'll cover your deductible." Illegal in Texas, and a preview of the corner-cutting you can't see from the ground.
- No physical local address or history. Storm chasers follow hail across the country. Your warranty is only as good as the odds the company is still in Houston in year five.
- No proof of insurance. Ask for the certificate of liability and workers' comp. A legitimate contractor sends it without flinching.
- Vague or missing decking terms. If the quote doesn't state a per-sheet decking price and an approval process, the surprise is being saved for mid-job, when your old roof is already in the dumpster.
- No written workmanship warranty. The manufacturer covers the shingles; only the installer covers the installation — and most roof failures are installation failures.
- Pressure to sign an insurance contingency on the first visit. Take the inspection, take the documentation, and take your time deciding who does the work.
Cost Questions, Answered Straight
What does a roof replacement cost per square foot in Houston?
Honestly, per-square-foot numbers are where most cost articles mislead you. Two houses with the same square footage can differ by thousands because of pitch, complexity, tear-off layers, decking condition, and material. Any per-foot figure precise enough to plan around is precise enough to be wrong for your specific roof. The useful number is a written quote from someone who has actually measured and inspected your roof — which is free and takes a day.
Why do quotes for the same roof differ by thousands of dollars?
Because they usually aren't quoting the same roof. One bid includes full tear-off, new underlayment, new flashing, corrected ventilation, disposal, and a workmanship warranty; another quietly reuses old flashing, skips ventilation, carries thin insurance, or leaves decking as a surprise change order. Compare scope line by line, not bottom lines. A quote that can't tell you exactly what's included is telling you something.
Can I finance a new roof?
Many Houston homeowners fund a replacement through home equity, personal lending, credit union loans, or contractor-arranged financing. If financing matters for your situation, raise it during the quote conversation and we'll walk through the options available at the time — before you commit to anything. The one payment structure to refuse from anyone: large cash up front before materials are on site.
Does a new roof raise my home's value?
Generally yes — a new roof is consistently one of the stronger-recouping exterior projects, and in practice it does something even more valuable in the Houston market: it keeps deals alive. An aging roof shows up in the option-period inspection, triggers insurance headaches for the buyer, and becomes a negotiating lever. A documented, transferable-warranty roof removes all of that. Just don't buy a roof purely as an investment — buy it when the roof needs it.
How does the quote process actually work?
Request a quote by form, call, or text. We inspect the roof — measurements, pitch, layers, flashing, attic ventilation, and any visible decking issues — then send a written quote with the scope spelled out,. No pressure visit, no expiring "today-only" price. If a repair is the smarter answer, the quote says repair.
Can a roofer waive or absorb my insurance deductible?
No — and in Texas it's illegal. Since 2019, Texas law (HB 2102) makes it a crime for a contractor to waive, absorb, rebate, or offset an insurance deductible, and insurers can require proof you paid it. A roofer offering a "free roof" by eating your deductible is proposing insurance fraud with your name on the claim, and it tells you how they treat the rest of the job. On an insurance-funded replacement, your out-of-pocket cost is your deductible — that's the honest math.
Is it cheaper to install new shingles over the old ones instead of tearing off?
Cheaper on the invoice, more expensive on the house. Layering over old shingles hides decking damage, traps heat that ages the new shingles faster in Gulf Coast summers, can void manufacturer warranties, and means the next replacement pays for a double tear-off. We replace roofs with full tear-off down to the decking, every time — it's the only way to know what you're actually building on.
More on what a proper replacement includes on our roof replacement page — or see everywhere we work →
Stop Guessing. Get Your Real Number.
Two minutes on our quote form with a few roof photos from the yard — or call or text (281) 686-9227 — and a roofer reviews them and comes back to you with a written roof replacement quote for your actual roof, no site visit needed. Without photos we come out and look first. Free, no pressure, and if a repair is the honest answer, that's what the quote will say.